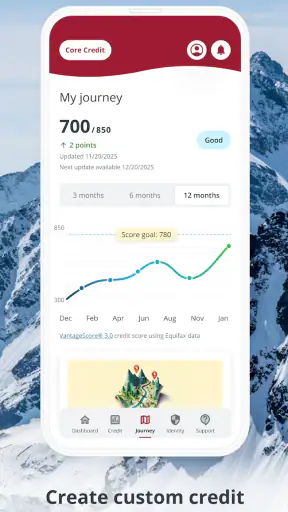
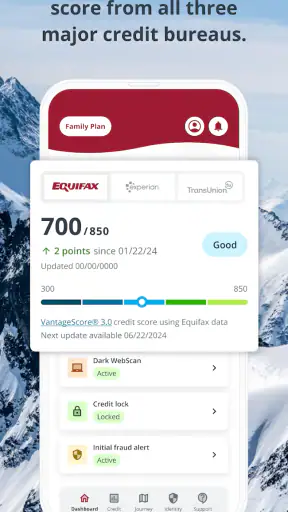
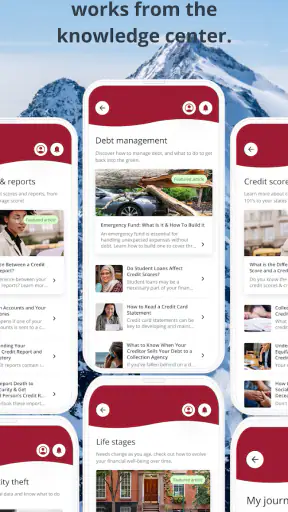
Managing credit from a phone sounds simple until an identity check fails, a sign-in screen loops, or the information you expected to see does not appear immediately. I found that myEquifax is most useful when treated as a focused credit-management tool rather than a complete personal-finance hub. It gives you a direct place to begin your credit journey, but the quality of the experience depends heavily on careful setup and knowing which problems belong to the app and which belong to your credit file.
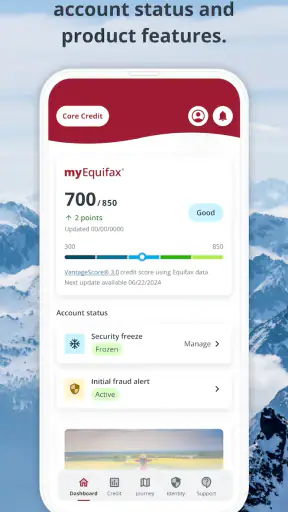
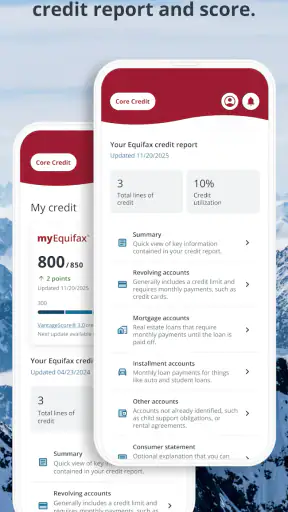
Developed by Equifax Incorporated, this free finance app is available for Everyone and supports devices running Android 8.0 or later. It was released on April 25, 2025, and the current version is 1.11.0. The store summary, “Start your credit journey,” is brief, but it points to the app’s main purpose: helping people interact with their Equifax credit information from a mobile device instead of relying entirely on a desktop browser or paper correspondence.
Its reception is encouraging, with an average rating of 4.6 from around 11 thousand ratings, while the app has passed 500 thousand installs. Those figures suggest that many users find the basic idea worthwhile, although they do not remove the need to prepare for the occasional account or identity-verification hurdle. In my experience, the most important question is not whether the app is attractive; it is whether it makes your particular credit task easier than the usual browser-based route.
Where the experience usually gets stuck
Sign-in and identity checks need patience
The first point of friction is usually account access. A finance app cannot afford to treat identity casually, so a new user should expect the setup to be more deliberate than opening a weather or shopping app. If the app asks for personal details, enter them exactly as they appear in your official records. Small differences in spelling, address formatting, or recently changed information can make an automated check harder, even when you are the rightful account holder.
I recommend avoiding repeated attempts with slightly different answers. That approach can create more confusion and makes it harder to remember which information was submitted. Instead, pause, check your details, and try again carefully. If the app presents a message that points you toward account help, follow that route rather than repeatedly closing and reopening the application.
Another common mistake is assuming that an unsuccessful verification attempt proves something is wrong with the credit file. It may only mean that the information entered does not match the records used for verification, that an address has changed recently, or that the session has expired. Keeping those possibilities separate prevents unnecessary worry and helps you choose the right next step.
Loading problems can look more serious than they are
Credit information is sensitive, so a page that takes longer to load can be unsettling. Before assuming that your account is damaged, check whether the device has a stable connection and whether other apps can reach the internet. Switching between a weak mobile signal and an unreliable wireless network can interrupt a secure session halfway through.
It is also worth closing the app completely and reopening it once, rather than tapping the same button many times. If the screen remains stuck, restarting the phone can clear a temporary system problem. These are ordinary steps, but they matter more in a finance app because an interrupted session can leave you unsure whether an action completed.
Do not use an old screenshot or a cached page as proof that your current information has changed. A screenshot is useful for your own notes, but it is not a live view. When reviewing anything important, open a fresh session and read the date or context shown on the screen before drawing conclusions.
Expect information to reflect reporting cycles
One of the most important practical lessons is that a credit app is not a live feed of every financial event. If you recently paid a balance, opened an account, corrected an address, or disputed an entry, the visible result may depend on when the relevant organization sends updated information and when that information is processed.
This means myEquifax can help you monitor what is currently associated with your Equifax file, but it should not be used to judge a payment only minutes after making it. For an everyday example, imagine paying a card balance before applying for an apartment. The sensible workflow is to keep your payment confirmation, allow normal reporting time, and then check the app later. If the expected update is still missing, investigate the reporting source instead of assuming the phone app caused the delay.
Setup checks that save time later
Prepare the account before you need urgent information
The worst time to discover a sign-in problem is immediately before a loan, rental, insurance, or employment-related deadline. I would install and configure the app during a calm moment, when you can read each prompt and keep your account details consistent. That gives you time to understand the access process without the pressure of needing an instant answer.
Use a current email address and a phone number you can access reliably. If your contact information changes later, update it through the appropriate account process rather than continuing to rely on an old recovery route. A finance app is only convenient when you can actually receive the messages or confirmations needed to regain access.
Make sure the device itself is supported. The app requires Android 8.0 or later, so an older phone may need an operating-system update or a different way to access your Equifax account. On a supported phone, keep the app updated to version 1.11.0 when an update is available through the normal store process. Updating is not a guaranteed fix for every issue, but it removes one avoidable source of incompatibility.
Use a deliberate privacy routine
Because this is a finance application, I would avoid setting it up while connected to an unfamiliar public network. A trusted home connection or mobile data is a better choice for entering personal information. I also avoid saving screenshots that reveal more account detail than necessary. If I need a record for a dispute or conversation, I capture only what is useful and store it somewhere private.
Screen locks and device updates matter here as much as the app itself. If somebody can unlock your phone, the protection offered by the account may be weakened in practice. A strong device passcode, current system software, and careful control of notifications are simple habits that make mobile credit management safer.
Separate app setup from credit-file expectations
Installing myEquifax does not automatically repair, refresh, or change your credit history. The app is a viewing and account-access tool, not a substitute for paying accounts on time or contacting the organization that supplied incorrect information. This distinction is easy to miss because the app places credit information close at hand, but visibility and correction are different jobs.
Before using the app, decide what you are checking. Are you confirming that an account is present, looking for an unfamiliar entry, preparing for a financial application, or simply learning how credit information is organized? A clear purpose makes the session shorter and reduces the temptation to treat every small change as an emergency.
Recovering a workflow after something goes wrong
When the sign-in process loops
If you return to the same sign-in screen repeatedly, start with the least disruptive checks. Confirm that the connection is stable, close the app, reopen it, and try once more without switching rapidly between multiple apps. If the problem continues, check that your device meets the minimum operating-system requirement and that you are using the current app version.
Do not immediately uninstall the app if you have not made sure you know your account credentials and recovery details. Removing an app can clear local state, but it does not solve an account-verification issue and may leave you repeating the same setup without understanding what failed. Reinstallation is better treated as a later troubleshooting step, not the automatic first answer.
If you use a password manager, confirm that it has not inserted an outdated email address or an extra space. Manual entry can be useful for one careful attempt. The goal is not to keep trying indefinitely; it is to identify whether the problem is a simple input mismatch, a connection interruption, or an account-level issue requiring support.
When a page appears incomplete
A partially loaded page does not necessarily mean that information has disappeared. First, refresh the session in a controlled way and check the connection. If other websites and apps are also slow, the wider network is a stronger suspect than myEquifax. If only this app is affected, note the exact screen and what you were doing when it happened.
That note becomes valuable if you need help. “It does not work” gives very little to investigate, while “the account opens, but the credit-information screen stops loading after sign-in” identifies a narrower problem. I would also record the approximate time, device model, operating-system version, and whether the issue happens on every attempt. Keep sensitive account details out of any public post or casual message.
When you see information you do not recognize
Unexpected information deserves attention, but not panic. First, read the entry carefully and check whether it could be an old address, a familiar company using a different name, or an account that belongs to another household member. Compare the details with your own records rather than relying on memory alone.
If something still looks wrong, preserve the relevant details privately and use the official dispute or support route associated with the account or credit file. The app can help you notice the issue, but it cannot by itself establish why an entry exists. Contacting the organization connected with the information may be more effective than repeatedly refreshing the same screen.
A useful habit is to keep a small timeline of what you noticed, when you contacted someone, and what documents support your position. This is more practical than taking dozens of random screenshots. It also helps you distinguish a genuinely unresolved issue from information that simply has not gone through its normal update cycle.
When the app is not the cause
Credit decisions happen outside the app
It is tempting to blame a mobile credit app after a rejected application, but myEquifax is not the decision-maker for a landlord, lender, insurer, or employer. A decision can involve information from other reporting sources, income, existing obligations, application details, or the organization’s own rules. Seeing a clean-looking screen in one place does not guarantee approval elsewhere, just as a rejection does not automatically mean the app displayed incorrect information.
This is where a dedicated credit app differs from a budgeting application. A budgeting app may help you categorize spending, plan bills, and view cash flow. myEquifax is more appropriate when your question concerns the Equifax side of your credit information. If your main goal is monthly budgeting, debt payoff planning, or tracking several bank accounts in one dashboard, a broader personal-finance tool may fit better.
It is not a replacement for every official route
The app is convenient for mobile access, but some users will still prefer a browser or direct support channel for complicated matters. A larger screen can be easier when comparing several records, organizing documents, or writing a detailed explanation. Someone who rarely uses smartphones, shares a device, or needs extensive account correspondence may find the usual web route more comfortable.
Likewise, people who want a complete view across multiple credit-reporting sources should not assume that one app represents every possible record. The relevant source depends on the issue you are investigating. myEquifax is strongest when the Equifax connection is the part you need to inspect; it is less suitable as a universal replacement for every credit-monitoring or financial-management service.
Who will benefit most
I see the clearest value for someone starting to understand credit, checking information before a major application, or wanting a convenient mobile entry point to Equifax. It can also suit a person who prefers short, occasional check-ins instead of maintaining a complicated financial dashboard.
The app is less compelling for somebody who already has a trusted desktop workflow and rarely needs mobile access. It may also frustrate users who expect instant updates after every payment or who want detailed budgeting tools in the same place. Choosing it makes sense when the specific task is Equifax credit access, not simply because it is free.
My practical verdict after using it
I like myEquifax as a focused starting point. Its free price removes a common barrier for people who want to begin checking their credit information, and its Everyone rating makes the intended audience broad. The app’s strongest quality is convenience: when the account is already set up and the connection is stable, a phone is a much easier place to perform a quick check than a full desktop session.
My reservation is that convenience can create unrealistic expectations. Verification may require careful matching, information may not update immediately, and a mobile screen cannot explain every reason a credit decision was made. The app is helpful when you use it as one part of a larger process: check the record, keep evidence, contact the relevant organization when necessary, and allow reporting changes time to appear.
If I were recommending it to a friend, I would say to install it before an urgent financial deadline, complete setup patiently, and keep your expectations tied to what a credit-information app can actually do. Use a secure connection, avoid repeated guesses during verification, and troubleshoot the device before assuming your file is at fault. Those habits address most of the avoidable friction.
My final recommendation is simple: choose myEquifax if you want a free, direct mobile way to begin working with your Equifax credit information. Skip it in favor of a budgeting app, a broader monitoring service, or a desktop workflow when your needs extend beyond that specific purpose. It is not a magic credit fixer, but used with realistic timing and careful account habits, it is a practical tool for turning an unfamiliar credit process into something you can check and understand more confidently.


